Bad Credit Loan Singapore | Loan for Black Listed

i-Credit is a licensed moneylender in Singapore that provides bad-credit loans to people turned down by banks, declined by other licensed moneylenders, or already carrying outstanding loans with several lenders. We have lent to borrowers across Singapore since 2009, from our office at ATRIX, 82 Lorong 23 Geylang, directly opposite Aljunied MRT. 

We assess your application based on what you earn now and what you already owe, not on your credit score alone.

If you already borrow from other moneylenders, we check how much room you have left under the Ministry of Law’s borrowing cap.

If there is room, we can lend. Fill out the application form to see if you are eligible.

Application Form

What is a loan for individuals with Bad Credit in Singapore

A bad credit loan in Singapore is an unsecured personal loan from a licensed moneylender for people who already have existing loans with various moneylenders or have been declined by banks.
 
i-Credit, a licensed moneylender, provides loans to these individuals to help with financial needs such as medical bills, rental arrears, car repairs, and other costs that cannot wait.
Individuals with bad credit in Singapore usually mean:
  • Low grade on your Credit Bureau Singapore (CBS) report
  • Late or defaulted accounts on that report
  • Unsecured bank debt above the Monetary Authority of Singapore (MAS) limit of 12 times your monthly income.
Banks decide mainly on your credit score. i-Credit, a licensed moneylender, looks at your current income and what you already repay. We use your payslips, CPF contribution history, bank statements, and Moneylenders Credit Bureau (MLCB) report to confirm you can afford the repayment before we lend.

What credit score does i-Credit Moneylender accept?

i-Credit has no minimum credit score. A low credit score, a thin credit file, or no credit history at all does not stop us from assessing you. We look at your income, your existing repayments and your MLCB record.
 
The MLCB report is the one i-Credit checks. It shows how much you already owe other licensed moneylenders and whether you are up to date.
 
Your situation
What it means
How i-Credit treats it
Bad creditLate payments or defaults on your CBS reportAssessed on current income and existing repayments
No credit historyNo CBS record yet. Common for new PRs, foreigners on a work pass and first jobbersAssessed on payslips, work pass and proof of address
Thin fileOne or two accounts, too little history for a bank to scoreAssessed the same way as no credit history

How to apply for a loan with Bad Credit Score?
Picture of Marcus

Marcus

i-Credit Loan Officer. Aljunied Branch

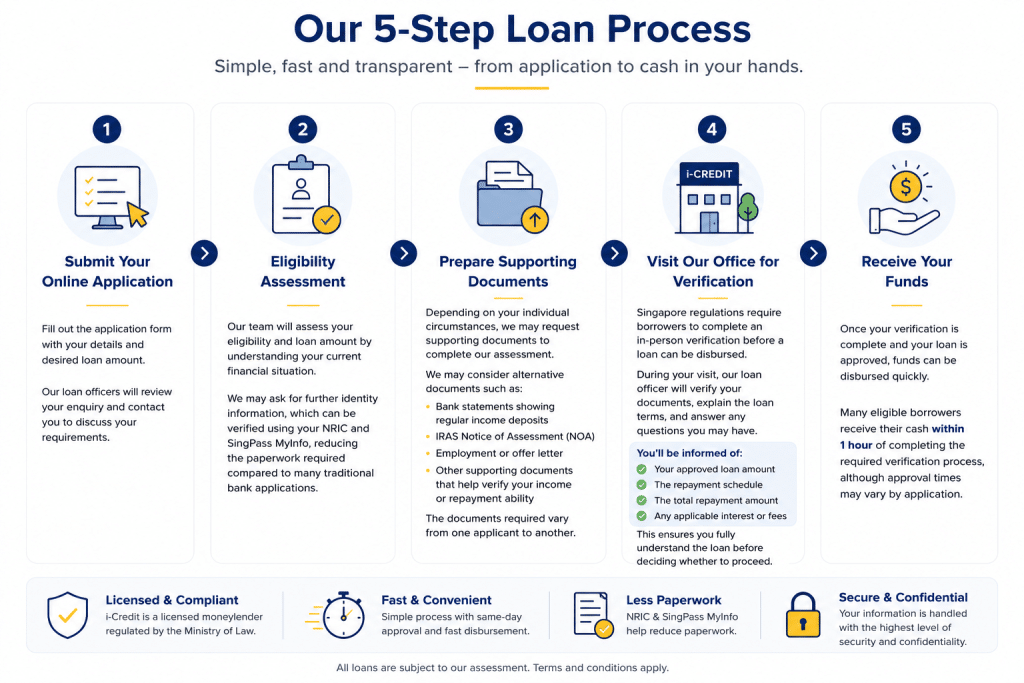
At i-Credit, we’ve simplified the application process and here’s what you can expect from start to finish.
  1. Fill in the online form. It takes about 2 minutes: your name, phone number, email, loan type, and amount.
  2. We call you. We respond within 15 minutes during our opening hours. We go through your income and existing loans and give you an indicative amount before you travel anywhere.
  3. Visit our office at ATRIX. We check your identity and documents, then explain the interest, fees, repayment schedule and total you will repay. The contract is in a language you understand, and you keep a copy.
  4. Sign and receive the money. Most complete applications are approved and paid out the same day.
Who are i-Credit's private lender loans for bad credit suitable for

You were declined by a bank

Traditional banks look at your CBS grade. Once your interest-bearing unsecured debt across all banks has been above 12 times your monthly income for three months in a row, banks cannot extend you more unsecured credit.
 
Applying to the next bank usually ends the same way, and every application is recorded on your CBS report.
 
i-Credit looks at your latest payslips or CPF contribution history and what you already pay each month. If the repayment fits your income, we can lend within the Ministry of Law caps.
There is no official blacklist in Singapore; people who say they are blacklisted usually mean a default on their CBS report, unpaid loans on their MLCB record, or bankruptcy.
 
A default on your record does not stop i-Credit from assessing you; we assess your eligibility for loans by reviewing your ability to support repayment.
If you have one or more loans with other licensed moneylenders and the last one turned you down, it’s usually the aggregate cap, not your credit score. The law limits how much you can owe all licensed moneylenders combined. Once you reach that limit, no licensed moneylender can lend you more, including i-Credit.
 
We can check your MLCB record and tell you how much room you have left under the cap.
If you’re working part-time, on shifts, commission-based, or paid without standard monthly payslips, you may still qualify if your income can be reasonably verified. Supporting documents may include statements reflecting regular deposits.
  • Work contracts, invoices, or payment records (where applicable)
  • Any available proof of consistent earnings over time
Your income proof is your Notice of Assessment, bank statements or platform earnings rather than a payslip. Our self-employed loan covers this.

What does a bad credit loan cost?

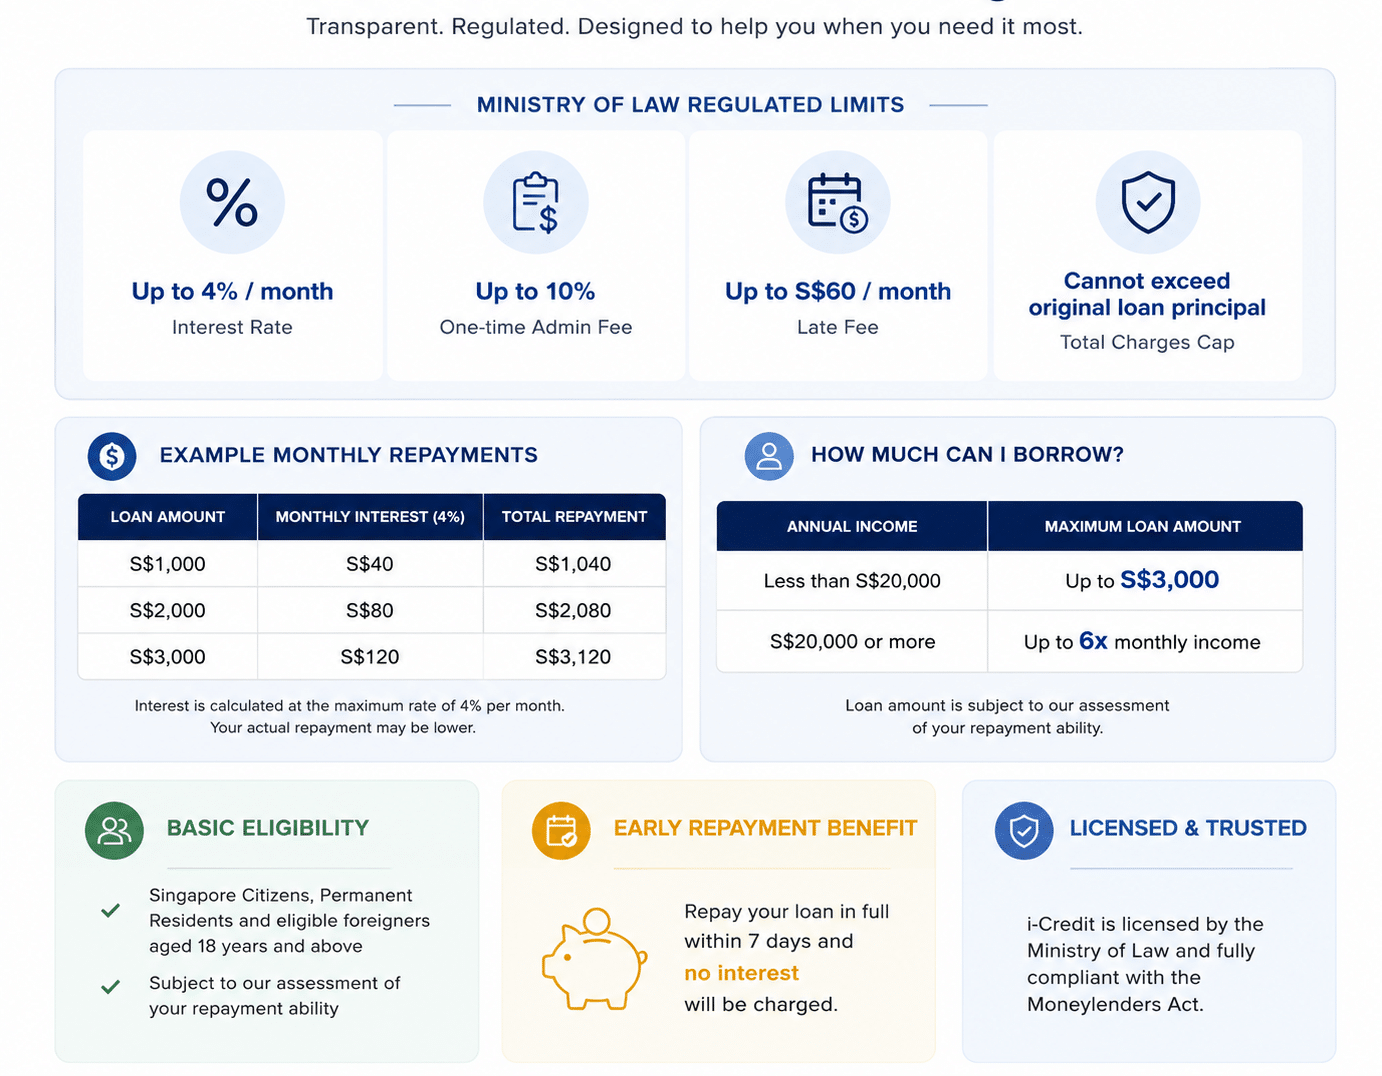
Every licensed moneylender in Singapore works under the same legal limits, whatever your credit score:

Interest rate
Up to 4% per month
One-time administrative fee
Up to 10% of the loan principal
Late payment fee
Up to S$60 per month
Total charges
Cannot exceed the original loan principal

Example Monthly Repayment

icredit borrowing limits

How do I repay a bad credit loan with i-Credit?

A bad credit record often starts with one missed payment. So we set your repayment dates around your payday. If you’re paid monthly, repay monthly. If you’re paid every fortnight, or weekly by a delivery or ride-hailing platform, choose that schedule instead.

  • Repay the whole loan within 7 days of receiving it and you pay no interest.
  • Before you sign, your loan officer takes you through each repayment date, the interest and every fee.

On-time payments keep your Moneylenders Credit Bureau (MLCB) record clean. That’s the record the next licensed moneylender will check. If a payment is going to be late, call us before the due date, not after. Late payments cost up to 4% a month in late interest on the overdue amount, plus a late fee of up to $60 a month.

Bad credit loan FAQs

Can I get a loan with bad credit in Singapore?

Yes. A licensed moneylender can lend to you if your income covers the repayment and you’re still under the Ministry of Law borrowing cap. At i-Credit we look at your MLCB record, your income and the loans you already have. You get a yes or no after that check, not before.
No. A licensed moneylender has to check your record and your income before lending, so nobody can promise approval up front. If a lender does, treat that as a sign it isn’t licensed. What actually helps your chances is a steady income, your documents ready on the day, and room left under the legal cap.
Your credit score doesn’t change the cap. Singapore citizens earning under $20,000 a year can borrow up to $3,000 in total from all licensed moneylenders. Earn $20,000 or more and the cap is 6 times your monthly income, so $21,000 if you earn $3,500 a month.
Most often because your total borrowing from licensed moneylenders has reached the legal aggregate cap, or because your income can’t support another repayment. Your MLCB report shows which. If you are at the cap, no licensed moneylender can lend you more, i-Credit included.
Yes, with other proof of income such as CPF contribution history, bank statements or a Notice of Assessment. Our team will tell you what we can accept when we call. See personal loan without proof of income.