Application Form
What is an i-Credit bankruptcy loan?
Can I get a personal loan while bankrupt?
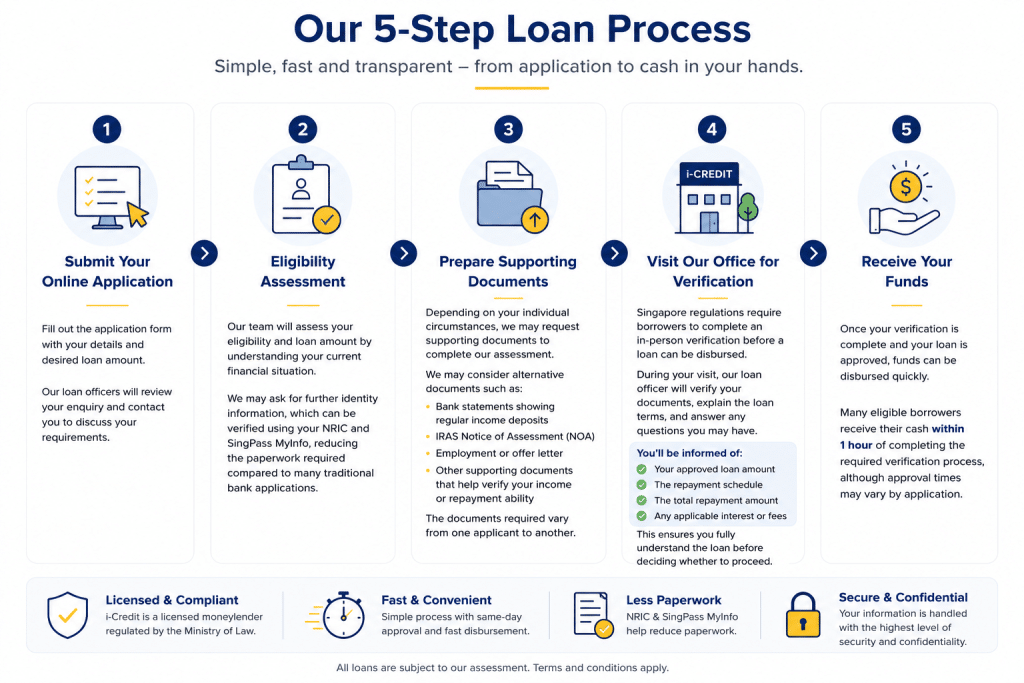
What is Bankruptcy Loan application process like?
Marcus
i-Credit Loan Officer. Aljunied Branch
Send the form during office hours and you can expect a reply in about fifteen minutes. The office visit itself, briefing through to cash in hand, takes about an hour.
- Fill in the online form. Two minutes. Tell us whether you are undischarged or discharged, and what you earn.
- We reply, usually within fifteen minutes during office hours. We will ask for your income and, if you are undischarged, your monthly contribution to the Official Assignee. You get an indication before you travel anywhere.
- Come to the Geylang office with your documents. Briefing, paperwork and disbursement take about an hour once your documents are complete.
- Sign and collect. The loan contract, the repayment schedule in writing, and the cash, in the same visit.
What documents do I need to apply for an i-Credit bankruptcy loan in Singapore?
- NRIC
- Singpass access
- Last 3 months of payslips or bank statements
- CPF contribution history through Singpass
- Proof of residential address
How much does a loan for Bankrupts in Singapore cost?
Every charge below is capped by the Moneylenders Rules. The caps are law and bind every licensed moneylender in Singapore, regardless of your credit history. A lender quoting you more than these figures is not licensed, and that is a fact you can check rather than a claim you have to trust.
| Interest rate | Up to 4% per month |
| One-time administrative fee | Up to 10% of the loan principal |
| Late payment fee | Up to S$60 per month |
| Total charges | Cannot exceed the original loan principal |
How much can a bankrupt person borrow in Singapore?
The ceiling is set by law, by annual income band, across all licensed moneylenders combined rather than per lender.
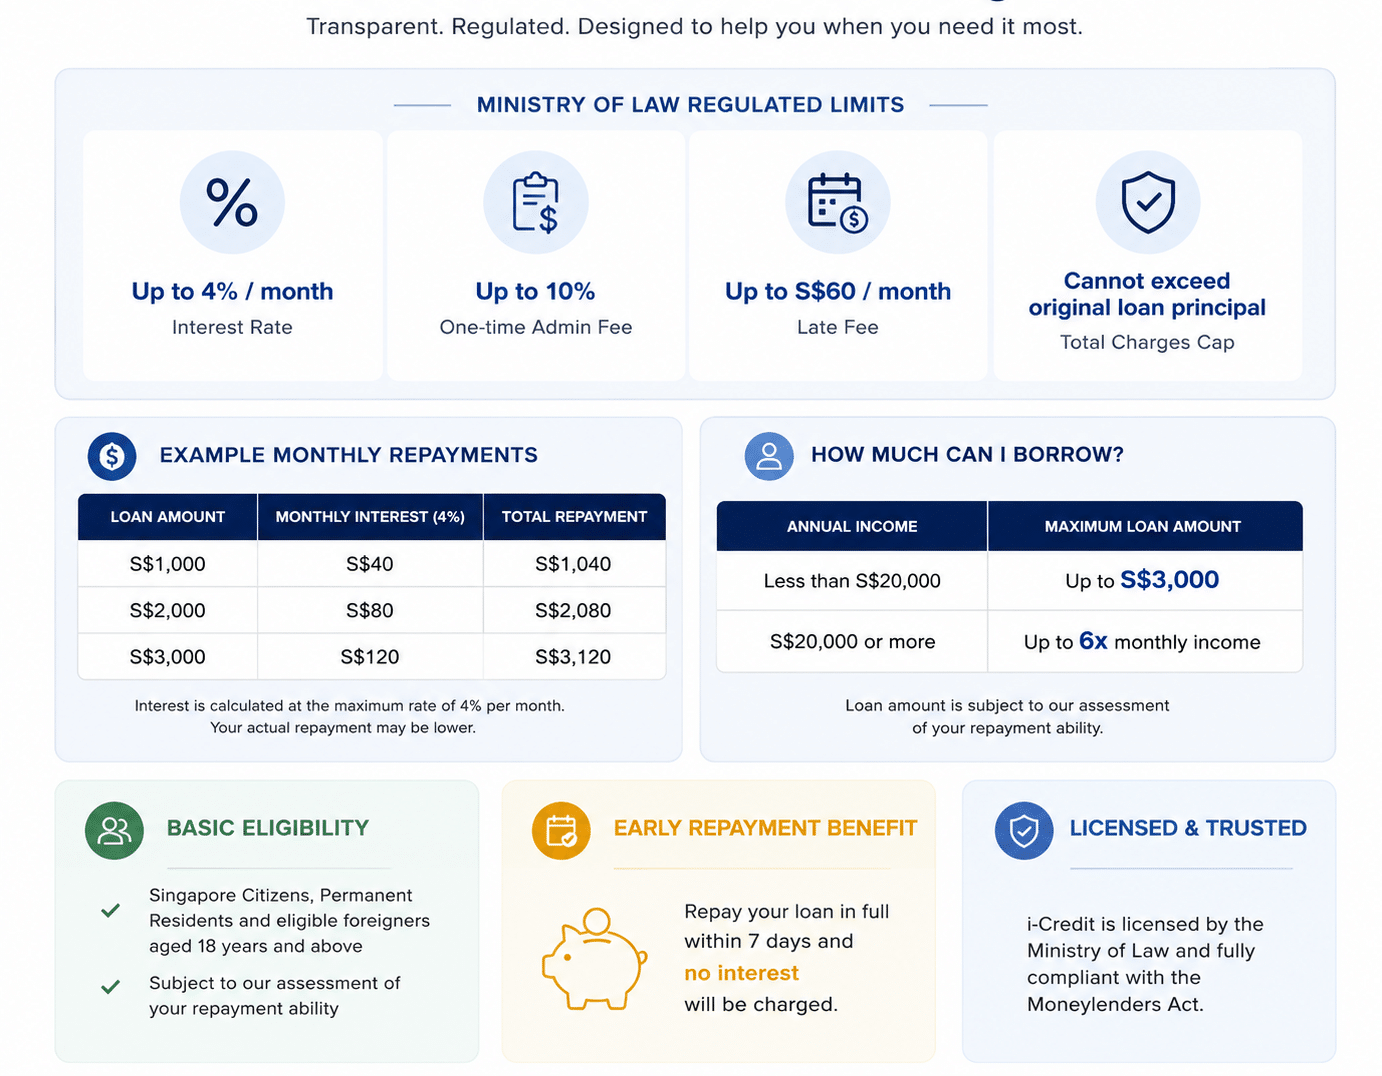
That is the ceiling. What you will actually be offered sits below it, because the assessment is affordability rather than entitlement. For an undischarged applicant the OA contribution comes off your income before we look at what a repayment would take, so expect a smaller figure than the band suggests.
Who Can Apply for i-Credit's Loan for Bankrupt?
You are undischarged, still working, and short this month
The order is in force, you are meeting the OA contribution, and you have been meeting it. Then something lands that the contribution schedule leaves no room for. A hospital bill for a parent. A fine with a date on it.
Every bank you approach declines on status, so nobody ever looks at the fact that you have paid your contribution eleven months running. We look at exactly that. The assessment is your current income, less the OA contribution, against the repayment. If what is left will not carry the repayment, we will tell you so rather than write the loan, because a second obligation you cannot meet helps nobody and can prejudice your discharge.
You are discharged, and the declines have not stopped
The order ended. The certificate is in a drawer. And the bank still says no, because the record outlives the order and bank policy keys off the record.
Two questions come up constantly here, so here are the answers. How soon after bankruptcy can you apply? Immediately. There is no waiting period for a licensed moneylender, discharged or not. Does discharge make the assessment easier? Yes, in one specific way: there is no OA contribution coming out of your income, so more of it is available to service a repayment, which usually means a larger amount and a shorter conversation. Bring the discharge certificate and it moves faster still.
You went bankrupt through a business, and you want to work again
While you are undischarged, you may not act as a company director or take part in the management of a business without leave. That restriction lifts on discharge.
So while the order is in force, what is available is a personal loan assessed on your employment income, not business finance. If the plan is to restart something, the sequence is employment first, discharge second, and the business after that.
You are under the Debt Repayment Scheme, not bankrupt
Different status, different rules. DRS participants are not bankrupts, the borrowing rules are not the same, and this is not your page. See loan while under the Debt Repayment Scheme, which answers the disclosure question for DRS specifically.
Undischarged or discharged: which one are you?
- Undischarged means the bankruptcy order made by the High Court is still in force. The Official Assignee, or a private trustee, is administering your estate. You are likely paying a monthly contribution towards it.
- Discharged means the order has ended and you hold a certificate of discharge. The record persists for a period afterwards, which is why banks keep declining you long after the order is gone.
Bankruptcy order | Still in force | Ended, certificate issued |
Who administers your estate | Official Assignee or private trustee | Nobody, the administration has closed |
Monthly contribution to the OA | Usually yes | No |
Duty to disclose when borrowing | Yes, at or above the statutory threshold | No statutory duty, but disclose anyway so the assessment is accurate |
Company directorship or managing a business | Restricted without leave | Restriction lifts on discharge |
Bank loans and credit cards | Declined on status | Usually still declined while the record persists |
Can i-Credit assess you | Yes | Yes |
What we assess on | Current income, less the OA contribution | Current income |
FAQ about Urgent loans for bankruptcies in Singapore
Can I get a loan if I am a bankrupt in Singapore?
Yes. A licensed moneylender may lend to an undischarged bankrupt, and the assessment is based on your current income and ability to repay rather than your credit history. It is assessed, not guaranteed, and if you are undischarged you have a duty to disclose your bankruptcy when obtaining credit at or above the statutory threshold.
How soon after bankruptcy can I apply for a loan?
Immediately. There is no waiting period for a licensed moneylender, whether you are undischarged or discharged. What changes with time is the arithmetic: while you are undischarged, the monthly contribution to the Official Assignee comes off your income before affordability is assessed, and after discharge it does not.
Can I get a loan with no credit check?
No, and any Singapore lender offering one is not licensed. A licensed moneylender is required to assess whether you can afford the repayment before lending, which means looking at your income. “Guaranteed approval” and “no credit check” are the clearest signal that you are dealing with an unlicensed lender. Check any lender against MinLaw’s Moneylenders list before you reply to them.
Can I get a business loan after personal bankruptcy?
Will taking this loan affect my discharge?
A disclosed, affordable loan sits alongside your contribution schedule and does not interfere with it. What prejudices discharge is failing to disclose credit at or above the statutory threshold, or taking on a repayment that causes you to miss contributions to the Official Assignee.
Do I have to come to the office?
Do I have to come to the office? Yes. Singapore law requires a licensed moneylender to verify your identity and sign the loan in person at the licensed premises. We are at 82 Lorong 23 Geylang, #05-02 ATRIX, 388409, directly opposite Aljunied MRT, open Monday to Friday 11am to 8pm and Saturday and Sunday 11am to 4pm.